Hey there, savvy drivers! Ever wondered how much auto insurance in Massachusetts would set you back? Well, buckle up because we’re about to take you on a ride through the ins and outs of car insurance costs in the Bay State. Whether you’re a seasoned motorist or gearing up to hit the road for the first time, knowing what affects your insurance rates can save you a bundle.
In this comprehensive guide, we’re diving deep into everything you need to know about auto insurance in Massachusetts. From mandatory coverages and cost breakdowns to money-saving tips and future trends, we’ve got it all covered. Get ready to be an informed driver who knows their stuff about insurance, all with a touch of Backlinko flair!
Understanding Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the highest auto insurance rates in the U.S.? It’s true. But why exactly are rates so high here?
The key lies in a combination of factors like the state’s unique no-fault insurance laws, high population density, and severe weather patterns. These elements can drive up your premiums significantly.
Factors Affecting Auto Insurance Rates in Massachusetts
Auto insurance rates in Massachusetts are influenced by a cocktail of factors. Your *driving record*, *age*, and *credit score* play a huge role. But here’s the kicker: your *location* and the *type of car* you drive can make a big difference too.
Insurance companies also look at the *weather patterns* in your area. If you live in a part of Massachusetts that gets pounded by snowstorms, expect to shell out more for coverage.
Mandatory Auto Insurance Coverages Required in Massachusetts
If you’re driving in Massachusetts, you can’t skip out on certain types of coverage. The state mandates that you have Bodily Injury to Others, Personal Injury Protection (PIP), and Damage to Someone Else’s Property.
These are non-negotiable. But there’s more:
- Bodily Injury to Others: Minimum $20,000 per person, $40,000 per accident.
- Personal Injury Protection (PIP): Covers up to $8,000 for medical expenses.
- Damage to Someone Else’s Property: Minimum $5,000 coverage.
Types of Auto Insurance Available in Massachusetts
Massachusetts offers a variety of auto insurance options beyond the mandatory ones. Here’s the deal: You can add collision, comprehensive, and uninsured/underinsured motorist coverage to your policy.
Here’s a detailed breakdown:
| Coverage Type | What It Covers |
|---|---|
| Collision | Pays for damages to your car after an accident. |
| Comprehensive | Covers non-collision-related damage like theft or natural disasters. |
| Uninsured/Underinsured Motorist | Protects you if you’re hit by a driver without sufficient insurance. |
Pro Tip: Adding comprehensive coverage can save you a heap of trouble (and cash) if your car is damaged by something other than a crash.
Common Auto Insurance Providers in Massachusetts
Shopping around for auto insurance? You’re in luck, because Massachusetts offers a plethora of providers. Here are some of the most common ones:
- Geico
- Progressive
- Liberty Mutual
- Allstate
- State Farm
When comparing providers, don’t just look at the price. Consider customer service, coverage options, and financial stability as well.
Cost Breakdown of Auto Insurance
Did you know that the average cost of auto insurance in Massachusetts is around $1,300 per year? BUT, there’s more to the story than just the average.
You see, auto insurance premiums can swing wildly based on several key factors. Let’s break it down so you can better understand what might affect your rates.
Typical Cost Ranges for Auto Insurance Premiums
In Massachusetts, the cost of auto insurance typically ranges between $1,000 and $2,000 per year. This variation stems from multiple factors that we will dive into next. The low end of the spectrum usually covers basic plans for low-risk individuals, while the higher end is for more comprehensive coverages or higher-risk drivers.
Impact of Age and Driving History on Costs
Age and driving history have a huge impact on what you pay. Young drivers under 25 often see higher rates because they’re statistically more prone to accidents. Here is the deal: A clean driving record can save you hundreds annually. On the flip side, accidents and violations can spike your premiums by up to 30% or more.
Pro Tip: Consider taking a defensive driving course to potentially lower your rates.
Comparison of Insurance Costs for Different Vehicle Types
Vehicle type is another significant factor influencing your insurance premiums. Sports cars typically cost more to insure than sedans or family vehicles. Here’s a quick comparison:
| Vehicle Type | Average Cost (Annual) | Low-End Range | High-End Range |
|---|---|---|---|
| Sedan | $1,200 | $900 | $1,500 |
| SUV | $1,400 | $1,100 | $1,700 |
| Sports Car | $1,800 | $1,500 | $2,500 |
| Truck | $1,300 | $1,000 | $1,600 |
Saving Money on Auto Insurance
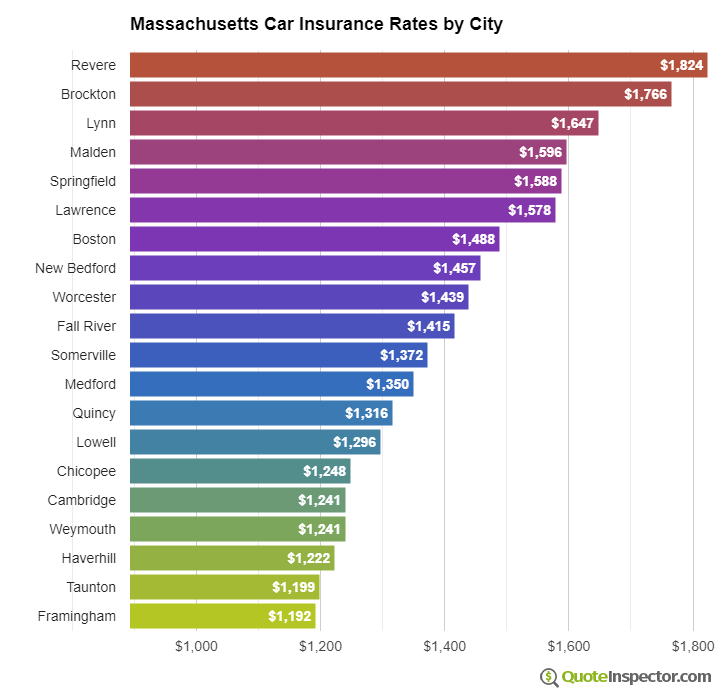
How much are you really paying for auto insurance? You might be shelling out more than you need to. The good news is, there are several ways to slash your insurance premiums in Massachusetts.
Many drivers feel stuck with their current rates, BUT there are smart strategies to lower your costs. From leveraging discounts to comparing quotes, the potential savings might surprise you.
Unlocking Discounts for Safe Driving and Bundling Policies
Insurance companies in Massachusetts love rewarding safe drivers. If you’ve got a clean driving record, you could snag a significant discount on your premiums. Plus, bundling your auto insurance with other policies like home insurance might save you up to 25%.
Here is the deal: you need to ask your insurer about any special programs or discounts. Many companies offer “good student” discounts for young drivers or reductions for installing anti-theft devices.
Pro Tip: Maintain a spotless driving record and consider defensive driving classes to enhance your eligibility for discounts.
Shopping Around and Comparing Auto Insurance Quotes in Massachusetts
Don’t settle for the first quote you get. Shopping around is vital to ensure you’re getting the best deal. Insurance rates can vary significantly between providers. On average, you could save over $400 per year just by switching insurers.
Step #1: Start by gathering at least three to four quotes from different companies. Step #2: Compare the coverage options and not just the price. Sometimes a slightly higher premium might offer better coverage.
Remember, it’s not just about finding the cheapest option, but the one that provides the best value.
Legal Aspects and Compliance
You might think of auto insurance as just another bill to pay. BUT in Massachusetts, it’s more than that — it’s a legal requirement. So what does this mean for you?
Having auto insurance isn’t just a smart move; it’s the law. The state of Massachusetts mandates car owners to have minimum insurance coverage. This ensures that you’re financially protected and in compliance with the law. BUT failing to have coverage could lead to significant consequences.
Massachusetts Auto Insurance Requirements
In Massachusetts, if you’re getting behind the wheel, you need to have compulsory coverage. Here is the deal: the state requires you to carry a minimum liability coverage of $20,000 per person and $40,000 per accident for bodily injury, plus $5,000 for property damage. Additionally, you need personal injury protection (PIP) of $8,000 and uninsured motorist coverage.
Penalties for Driving Without Insurance
Driving without insurance in Massachusetts is no joke. Here’s a quick rundown of the penalties you could face:
- Fines: You can be fined up to $5,000.
- License Suspension: Your driver’s license could be suspended for up to 60 days to a year.
- Jail Time: Yes, you might even spend a year behind bars.
- Additional Fees: You’ll pay a reinstatement fee to get your license back.
Pro Tip: Always have proof of insurance in your vehicle to avoid unexpected penalties.
Role of the Massachusetts Registry of Motor Vehicles
The Massachusetts Registry of Motor Vehicles (RMV) plays a critical role in auto insurance compliance. They are responsible for verifying that every vehicle on the road is insured. The RMV uses an electronic system to check your insurance status, and if they find you’re lacking, it’s game over. You could face penalties, and your registration might be suspended.
Claims Process and Customer Service
Did you know that 32% of drivers find the claims process more stressful than the accident itself? Filing an auto insurance claim in Massachusetts doesn’t have to be a nightmare. Let’s break it down step-by-step so you can handle it like a pro.
When you’re involved in an accident, the first 24 hours are crucial. Contact your insurance company as soon as possible. Some companies even offer a claims app where you can upload photos and details right from the scene.
Step-by-Step Guide to Filing a Claim
Here is the deal: filing a claim can be streamlined if you know the process. Step #1: Gather all relevant information—drivers’ details, photos of the incident, and witness contacts. Step #2: Contact your insurer and provide them with this information. Be accurate and honest.
Step #3: An adjuster will be assigned to evaluate your claim. They might inspect the damage in person or ask for additional documentation. Step #4: Once assessed, you’ll receive a settlement offer. Review it carefully and ask questions if something isn’t clear.
Pro Tip: Keep a copy of all documents and communications for your records.
Comparing Customer Service Ratings
Some companies make claims an effortless process, while others can turn it into a bureaucratic headache. According to the latest survey, Company A leads in customer satisfaction with a 91% approval rating. In contrast, Company B trails behind with just 75%.
| Insurance Company | Customer Service Rating |
|---|---|
| Company A | 91% |
| Company B | 75% |
| Company C | 83% |
Look for insurers with high ratings in both claims handling and overall satisfaction to ensure a smooth experience.
Guidelines for Choosing Based on Claims Handling
Here is a fact: not all insurers are created equal. When selecting an insurance provider, prioritize those known for efficient claims handling. Check online reviews and ratings.
Speak with friends or family for recommendations. Make sure to ask about their personal experiences with claims, response times, and customer support.
Pro Tip: Choose a company with 24/7 claims support and digital processing options.
By following these guidelines, you can ensure a better experience when you need your insurance the most.
Future Trends in Auto Insurance
The world of auto insurance is rapidly evolving, and Massachusetts is no exception. Are you ready for the changes that are coming?
With technology advancing at lightning speed, the way insurers calculate your premiums is set to change. Not to mention, emerging coverage options could completely redefine what you think you know about auto insurance.
Impact of Technology on Auto Insurance Pricing
The influence of technology on auto insurance pricing is nothing short of revolutionary. Telematics, or in-car data collection, is now allowing insurers to tailor premiums based on your driving habits. You heard that right; drive safely, pay less!
But the real game-changer? Predictive analytics. This tech uses AI to predict the risk of accidents and adjusts premiums accordingly. It’s like your Crystal Ball, but for auto insurance. Here is the deal: If you’re not tech-savvy, you’re missing out on potential savings.
Emerging Trends in Coverage and Policy Offerings
What if I told you that pay-per-mile insurance is gaining traction? Yes, if you’re someone who drives less, you could be shelling out less, too. This trend is especially appealing in urban areas where car usage is lower.
Another trend to watch? Bundling options that now include cybersecurity coverage for connected cars. Hackers beware! Your insurance policy might just have you covered. It’s all about creating a comprehensive safety net for policyholders.
Environmental Factors Influencing Policies
Massachusetts is no stranger to environmental shifts, and neither is its auto insurance market. Climate change impacts, like increased flooding, are forcing insurers to reconsider risk levels and adjust coverage accordingly.
As the state pushes for greener energy and electric vehicles, insurers are offering incentives for electric car owners. Pro Tip: Switching to an electric vehicle could not only save you gas money but also reduce your insurance costs.
But be warned; environmental risks mean that insurance companies might raise premiums in areas more prone to natural disasters. So, staying informed is your best defense.
Summary
So there you have it, folks! Now you’re equipped with the knowledge to navigate the auto insurance landscape in Massachusetts with ease. Remember, understanding the factors that affect your rates and making informed choices can lead to significant savings. Stay savvy, keep comparing, and drive safely. Until next time, happy insuring!
Common Queries
What factors affect auto insurance rates in Massachusetts?
Auto insurance rates in Massachusetts are influenced by factors such as your age, driving history, type of vehicle, and coverage options chosen.
What are the mandatory auto insurance coverages required in Massachusetts?
Massachusetts law requires drivers to have liability coverage, personal injury protection (PIP), and uninsured motorist coverage.
How much does auto insurance typically cost in Massachusetts?
Auto insurance premiums in Massachusetts typically range from $1,000 to $2,000 annually, depending on various factors like age and driving history.
How can I save money on auto insurance in Massachusetts?
To save money on auto insurance, you can shop around for quotes, take advantage of discounts for safe driving, and consider bundling policies.
What happens if you drive without insurance in Massachusetts?
Driving without insurance in Massachusetts can result in fines, license suspension, and even vehicle impoundment.
How does technology impact auto insurance pricing in Massachusetts?
Technology such as telematics and advanced safety features in vehicles can lead to lower insurance premiums by reducing the risk of accidents.
What are emerging trends in auto insurance coverage in Massachusetts?
Emerging trends include usage-based insurance and coverage options tailored to electric vehicles, reflecting the shift towards more sustainable driving.
